How CFIUS Reviewed 347 Foreign Deals for National Security Risk in 2025
The Committee on Foreign Investment in the United States evaluates cross-border deals for national security risks.
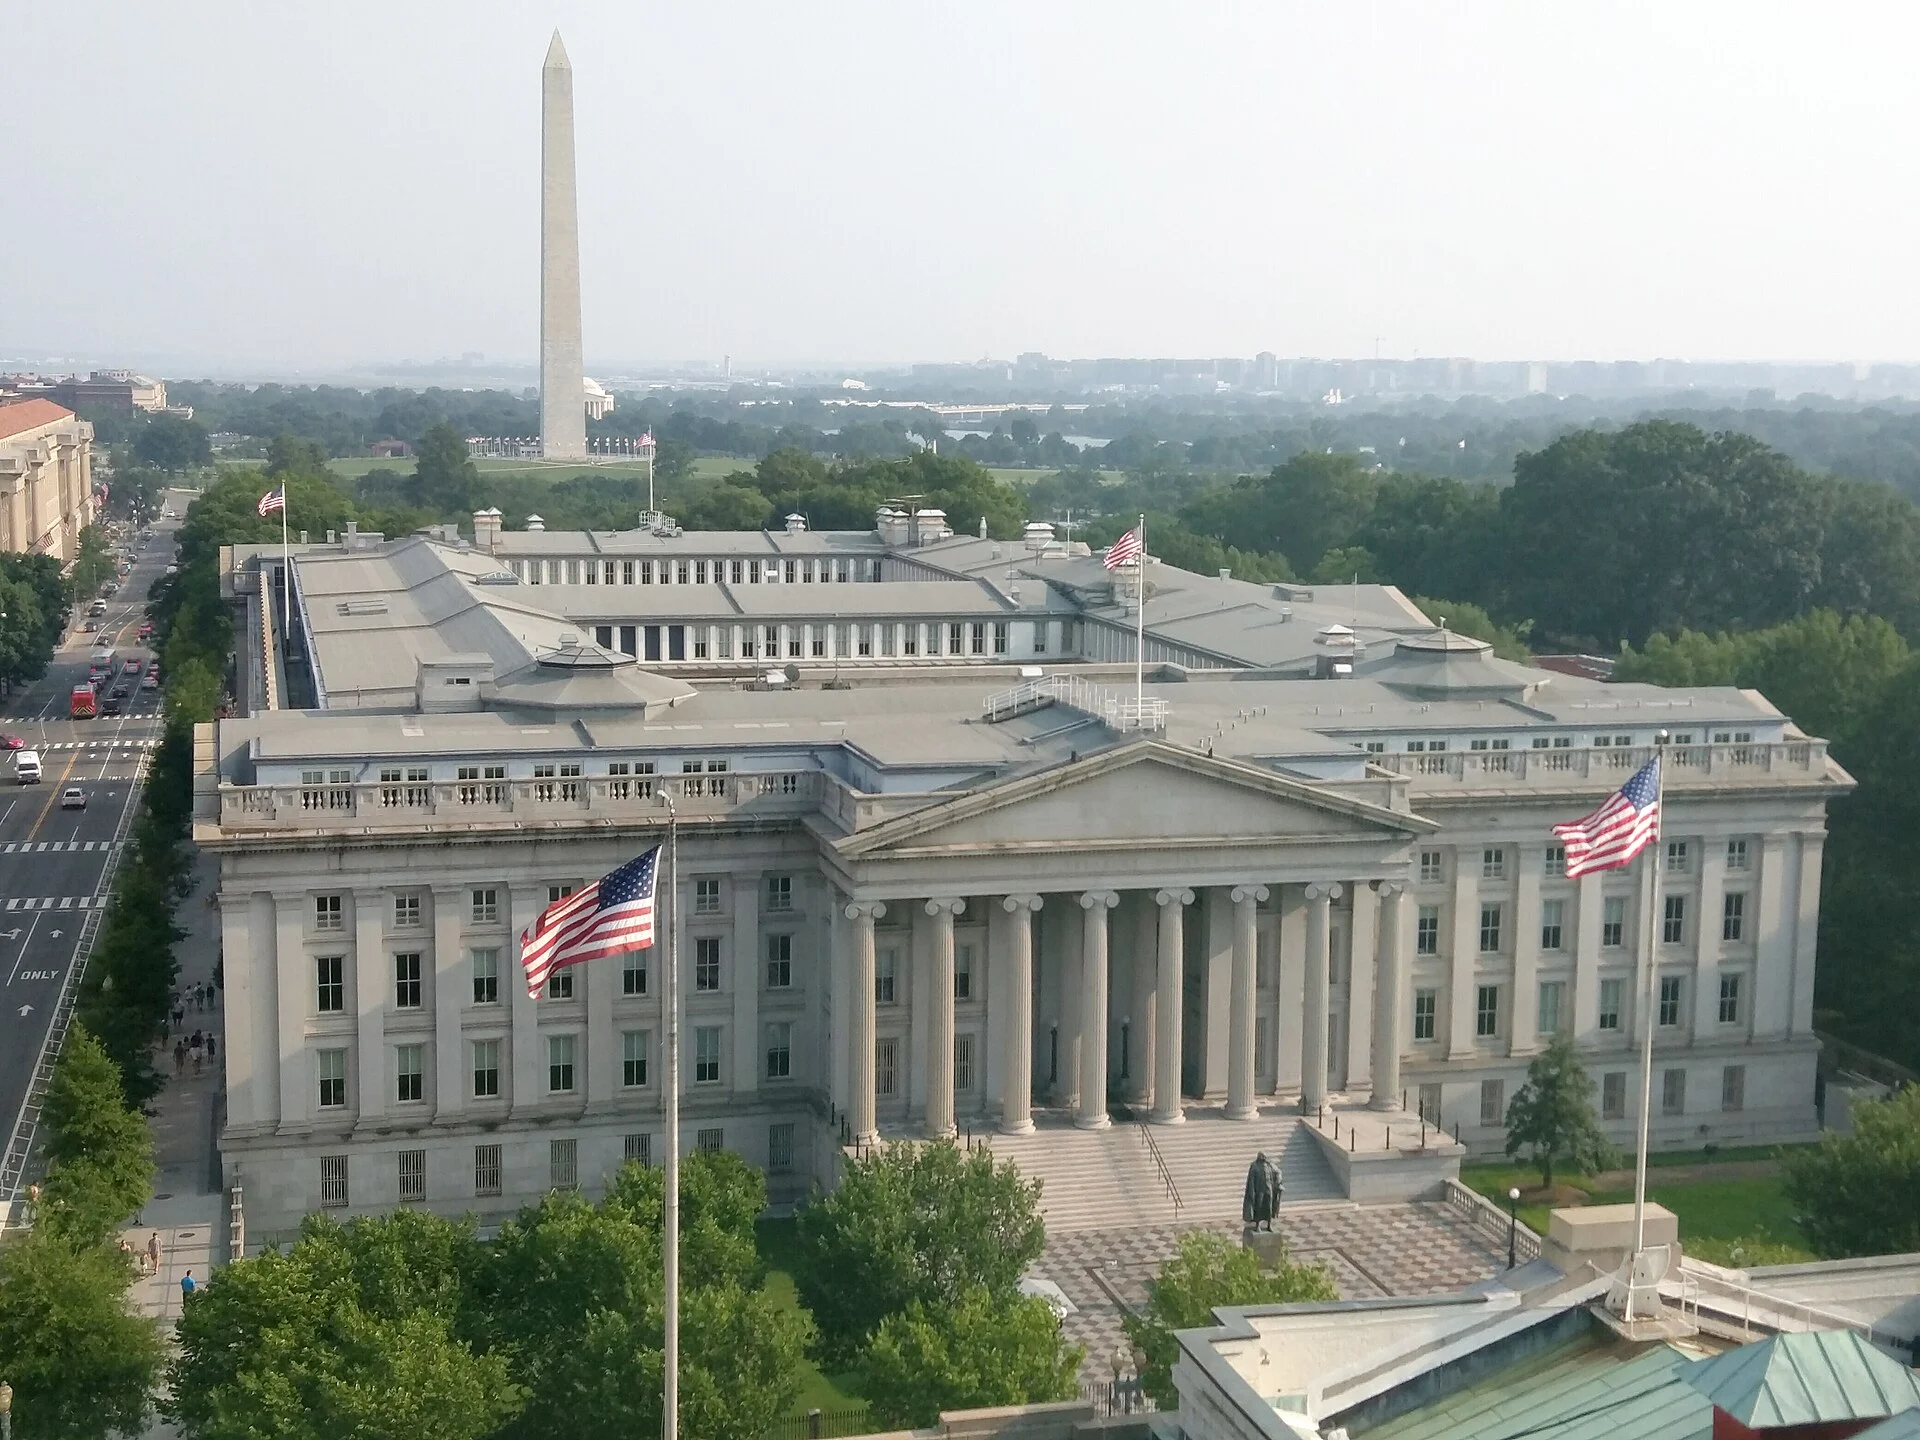
The Committee on Foreign Investment in the United States (CFIUS) is an interagency body chaired by the Treasury Department that reviews foreign acquisitions and investments in American companies to determine whether they pose national security risks. Any foreign investor considering a significant stake in a U.S. business—particularly in sensitive sectors—must navigate CFIUS’s filing requirements and review process, which can delay or block deals entirely. The committee processed 347 covered transactions in 2025, up from 325 in 2024, reflecting both growing cross-border investment and heightened national security scrutiny.
CFIUS has authority under Section 721 of the Defense Production Act of 1950 to examine transactions involving foreign investment in U.S. businesses and real estate. The committee determines whether a deal affects U.S. national security—a term that encompasses far more than military or defense concerns. A foreign investor’s identity, the sector it is entering, the type of control being sought, and what information or assets the target company possesses all factor into whether CFIUS will launch a formal review. For international companies seeking to enter or expand in the American market, understanding CFIUS’s jurisdiction and procedures is essential to deal planning.
What Triggers a CFIUS Review
The committee focuses on three categories of concern: critical technology, critical infrastructure, and sensitive personal data—collectively known as TID businesses. Foreign investment in critical technologies is the most common trigger. These include defense articles on the U.S. Munitions List, items subject to export controls under the Commerce Control List, nuclear equipment, and emerging foundational technologies. In 2025, CFIUS reviewed 166 covered transactions involving U.S. critical technology companies, representing a significant portion of its caseload.
Critical infrastructure encompasses energy, telecommunications, transportation, and related systems. Sensitive personal data refers to information about U.S. citizens maintained or collected by a U.S. business. CFIUS also reviews real estate transactions near military installations, missile fields, U.S. ports designated as sensitive, and government facilities. Beyond these sectors, the committee retains discretion to review any transaction where a foreign government, directly or indirectly, may acquire control of a U.S. business.
The definition of control is broad: it includes any ability to determine, direct, or decide important matters affecting a business. Even minority investments can trigger review if they confer certain rights—such as board representation, veto power over corporate decisions, or access to sensitive information. A foreign government investor faces the strictest scrutiny. Transactions by a foreign government, or by a foreign person in which a foreign government holds a significant stake, can be reviewed even when they fall below typical thresholds that would trigger mandatory filing.
CFIUS in Numbers
In 2025, CFIUS processed 347 covered transactions (207 written notices and 140 declarations), up from 325 in 2024. The committee cleared 67 percent in initial review periods. Critical technology acquisitions accounted for 166 of these transactions. CFIUS also investigated 90 non-notified transactions and actively monitored 234 mitigation agreements from prior deals.
Mandatory vs. Voluntary Filings
Not all foreign investments require a CFIUS filing. The committee distinguishes between mandatory and voluntary submissions based on what is being acquired and who is acquiring it. Mandatory filings are triggered in two primary scenarios: when a foreign government obtains a substantial interest in a TID business, or when any foreign investor acquires control of a U.S. business involved in critical technologies subject to export control.
Below these thresholds, filings are voluntary but increasingly common. Many foreign investors file anyway through declarations or written notices to obtain clarity and safe harbor protection, even when filing is not mandatory. This reflects the market reality that CFIUS’s jurisdiction is not always clear-cut, and the cost of proceeding without review and later facing an enforcement action outweighs the filing burden. In 2025, CFIUS processed 347 covered transactions: 207 written notices and 140 declarations. The volume of declarations rose significantly, though notably, CFIUS requested that 36 of these declaration filers upgrade to full written notices for more thorough review—more than double the 17 upgrades requested in 2024—suggesting that the committee is raising its scrutiny threshold for short-form filings.
The shift in filing patterns also reflects changes in who is investing in the United States. Japan displaced China as the leading source of overall filings in 2025, with Japan leading in declarations (18 filed), followed by France (14) and Singapore (13). This geographic shift likely reflects both policy changes toward strategic allies and CFIUS’s tighter review of acquisitions by or connected to certain foreign governments.
The Two-Path Review Process
CFIUS offers two pathways with different timelines and depths of review. A declaration is an abbreviated, short-form filing that triggers a 30-day assessment period. This pathway is available for transactions that meet certain criteria: generally, they must not involve a foreign government, must not result in control of a TID business by a foreign person, and must not involve critical infrastructure. The declaration process is faster but lighter—CFIUS conducts an initial assessment and either clears the transaction or requests the filer to submit a full written notice.
A written notice is a more detailed submission that initiates a standard 45-day review. This is the pathway for transactions involving foreign governments, control of TID businesses, or critical infrastructure, as well as for declarations that CFIUS decides warrant deeper examination. During the 45-day period, the committee can request additional information, seek mitigation measures, or recommend to the President that the transaction be suspended or prohibited. According to CFIUS’s 2025 annual report, the committee cleared 67 percent of distinct transactions in either the 30-day assessment period or the initial 45-day review period, meaning the majority of deals proceed without escalation.
Parties can request a pre-filing consultation before formally submitting documents to discuss the transaction and identify potential national security concerns. This informal step, available at no cost, can clarify whether a transaction is likely to trigger concerns and whether the investor should expect a quick clearance or substantial conditions. If CFIUS raises issues during the initial review, it may negotiate mitigation measures—restrictions on hiring foreign nationals, limitations on board representation, requirements for operational safeguards, or regular compliance certifications. These agreements remain under active monitoring; in 2025, CFIUS actively monitored 234 mitigation agreements from prior transactions.
Safe Harbor and the Cost of Non-Filing
Transactions cleared during the initial review receive safe harbor protection, meaning CFIUS cannot reopen its investigation based on the facts as presented in the filing. This safe harbor is valuable for international investors because it eliminates the risk of a deal being unwound years after closing. However, safe harbor protection does not apply if parties fail to comply with mitigation agreements, provide false or materially misleading information, or subsequently engage in conduct that was prohibited by the CFIUS review.
The risk of proceeding without filing can be severe. In 2025, CFIUS investigated 90 cases involving non-notified transactions—deals that were completed without a CFIUS filing and that later came to the committee’s attention. These investigations can result in enforcement actions, requiring the foreign investor to divest or restructure the investment, and exposure to civil penalties. The enforcement investigation alone disrupts the investor’s plans and management of the acquired business.
A foreign investor’s identity, the sector it is entering, and what information or assets the target company possesses all factor into whether CFIUS will launch a formal review.
Sector Concentration and the Risk Profile
CFIUS’s caseload is heavily concentrated in certain sectors. Finance, Information, and Services sectors accounted for 50 percent of non-real estate notices filed in 2025, while Manufacturing represented 39.5 percent. Within these sectors, companies that handle sensitive personal data, operate critical infrastructure, or develop controlled technologies face the highest review risk.
Foreign direct investment in critical technology received particular attention in 2025, with 166 covered transactions involving U.S. critical technology companies reviewed by CFIUS. This represents a substantial portion of the committee’s overall caseload and reflects the priority the U.S. government places on ensuring that advanced technology remains under domestic control or allied ownership. A foreign acquirer entering the semiconductor, artificial intelligence, biotechnology, or advanced materials sectors can expect heightened scrutiny and a higher likelihood of mitigation conditions.
Enforcement, Penalties, and Compliance Obligations
Failure to file a mandatory declaration or notice, non-compliance with CFIUS-imposed mitigation terms, or material misstatements in filings can trigger enforcement action. CFIUS derives its enforcement powers from Section 721 of the Defense Production Act and can impose civil penalties, with real-world penalties ranging from $100,000 to $60 million depending on violation severity.
Beyond monetary penalties, enforcement consequences can be severe. CFIUS can revoke safe harbor protections, reopen closed investigations, require the investor to divest the acquired company, and demand ongoing compliance filings for up to five years after a deal closes. The agency has substantially increased its enforcement resources and staff in recent years, dedicating more attention to monitoring transactions after they close and investigating non-notified deals. For a foreign investor, this means that even a deal that was not formally flagged at the time can later become the subject of a compliance investigation.
The Known Investor Program and Future Streamlining
In May 2025, Treasury announced the Known Investor Pilot Program, designed to streamline reviews of transactions from trusted allies and partners. Under this program, CFIUS collects detailed information from foreign investors in advance of formal filings, with the goal of facilitating greater investment from strategic partners while maintaining national security oversight. The program reflects a policy shift toward distinguishing between investors from countries the U.S. considers allies and those from countries where national security concerns are higher.
The Known Investor Program addresses a structural problem in the CFIUS process: the 45-day standard review timeline, combined with the unpredictability of whether mitigation will be required, creates significant friction in the cross-border market. A foreign acquirer planning a transaction cannot reliably predict when the deal will close, whether conditions will be imposed, or what those conditions will require. For large acquisitions, this uncertainty can be deal-breaking. The program aims to reduce this friction for investors from allied countries by pre-vetting them and their proposed structures.
Treasury was seeking public input as of early 2026 on how to expand and formalize streamlined procedures, indicating that CFIUS may implement broader regulatory reforms to increase review efficiency in the coming years. Potential changes could include expanded declaration pathways, faster clearance for certain sectors, or broader pre-approval for known investors. However, any streamlining will likely remain limited to transactions involving allies, as CFIUS’s national security mandate requires continued scrutiny of investors from countries viewed as potential competitors or adversaries.
Photo: MeanieHyaena · CC BY 4.0 · via Wikimedia Commons